25 Basis Points And A New Forecast: How The Fed Broke Its Year-Long Hold On Rates
Fed hikes rates to 3.75% and signals another hike as inflation stays elevated.
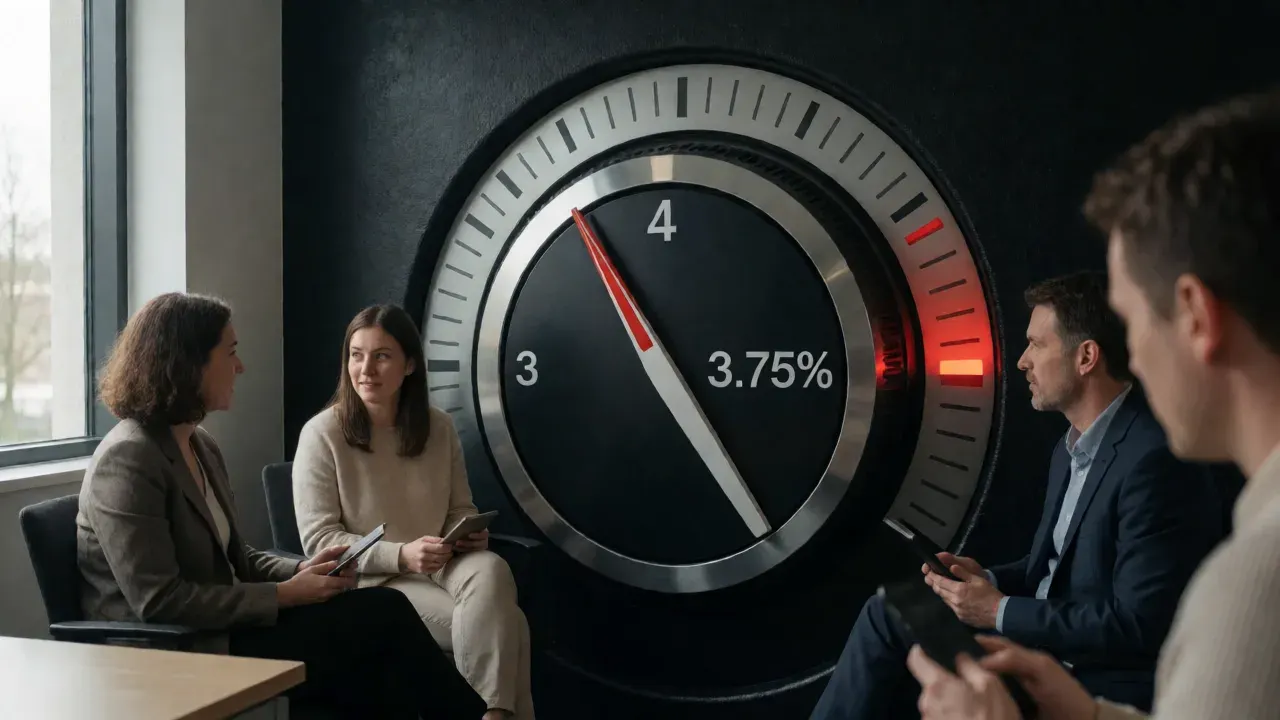
The Federal Reserve broke a year-long vigilance on Wednesday by approving its first interest rate hike in more than three years. The decision to raise the federal funds rate by 25 basis points marks a structural shift in monetary policy as markets priced in a better than 90 percent chance of the move weeks prior. The policy move brings the overnight funds rate to a new target range of 3.75 percent to 4 percent. This action represents the first policy shift since the FOMC paused its tightening cycle in July 2023. The central bank signaled that this move is not an isolated event but the opening salvo in a renewed battle against price stability.
The mechanics of this policy shift rely on the central bank's ability to influence the velocity of money and the cost of capital across the economy. By increasing the cost of borrowing, the Federal Reserve aims to cool demand for goods and services without triggering a sharp contraction in employment. In a statement released following the meeting, the committee noted that inflation remains elevated and that today's action supports a timelier return to the 2 percent goal. The vote was unanimous, with the Federal Open Market Committee approving the increase by a margin of 12 to 0. This collective action suggests a rare moment of unified consensus among policymakers regarding the current economic trajectory.
Chairman Kevin Warsh emphasized during a news conference that inflation has been 'too high ... for too long.' The chairman highlighted that the committee must be confident that underlying inflation is moving to its objective clearly and at a sufficient speed. Warsh pointed to recent economic reports which indicated a strong economy including the labor market but noted that inflation remained above the central bank's target. He also added that tension in the Middle East contributed to the decision, citing the impact of higher fuel costs from the Iran war and lingering tariff impacts on the supply chain. 'All three of those things lend themselves to a firm unanimous decision today,' Warsh stated.
The Federal Reserve's projections released Wednesday provide a granular view of future monetary policy paths. The dot-plot grid of individual officials' expectations indicated that 16 of the 18 participants expected another rate increase. Four of those officials saw two more hikes as possible while two participants expected the committee to stop at one hike. There are no increases penciled in for subsequent years, with one cut each indicated for 2028 and at least one for 2029. This distribution suggests the Fed views the current inflationary environment as a persistent drag on economic growth rather than a temporary fluctuation.
Market participants reacted immediately to the shift in policy stance. The S&P 500 rose following the announcement while Treasury yields surged. The 10-year note has risen about a quarter percentage point since Warsh's remarks at the Fed's Jackson Hole, Wyoming, symposium on Aug. 28. The benchmark is up about a full percentage point since its February low. The 2-year note, which is most sensitive to rate expectations, has seen even sharper gains. Borrowing costs have also been on the move, with a 30-year fixed-rate mortgage soaring to 7.19 percent. This rate is up some 38 basis points since the Jackson Hole speech and more than a full percentage point from a year ago according to Mortgage News Daily.
Despite the market acceptance, the rationale behind the hike involves complex tradeoffs between price stability and employment. The committee lowered its outlook for the unemployment rate to 4.1 percent, down 0.2 percentage point from June. The worry now is that the duration of energy prices could raise inflation expectations and start to spread through the economy. Economists also identify expanded investment in artificial intelligence as a potential inflationary factor. Furthermore, the 'transitory' episode from a few years ago is fresh in policymakers' minds, as the Fed initially thought the supply and demand shock from the Covid pandemic would fade. Instead, inflation readings hit 40-year highs before the Fed decided to act.
The Fed rarely moves once, as policymakers generally eschew incremental decisions when they think inflation is too high or when growth is too slow. At this week's meeting, the vote on a second hike was a fairly close call, with eight officials pointing to another hike, six seeing the funds rate holding steady and four envisioning cuts. In July, the debate generated considerable dissent, with three FOMC members voting against the decision to hold, preferring instead a quarter-point hike. In the wake of the decision, Treasury yields were lower, a signal that investors were encouraged by the central bank's attempt to tamp down inflation. Yields and prices move in opposite directions.
Brad Conger, chief investment officer at Hirtle & Co., described the moment as a potential return to 'Volckerian decisiveness' as opposed to the 'eternal sycophancy of the Powell era.' 'Today's FOMC could mark the moment when the FOMC regained a measure of spine,' Conger said. 'There were many arguments for standing still. But for once, the committee sided with main street.' The move signals a commitment to the 2 percent inflation target that may redefine the economic landscape for the remainder of the year.
First reported by CNBC: Finance.
More in Business
- IMF Chief Warns of Economic Divergence and Debt Risks Amid Artificial Intelligence Boom
Kristalina Georgieva suggests that while AI could significantly boost global growth, it simultaneously threatens to widen inequality and exacerbate inflationary pressures and public debt burdens.
- California Limits Utility Profits and Expands Home Energy Role
Gov. Gavin Newsom signed laws capping utility returns on lower-risk projects and accelerating virtual power plant development.
- Lyft to Pay $272.5 Million in Record California Wage-Theft Settlement
Largest such settlement in state history resolves claims that Lyft misclassified drivers as independent contractors from 2016 to 2020, denying them core wage protections.