Trade War 3.0: Why Your AI Chips Are Still Made in China and Trump Can't Stop It
The second summit of the year promises nothing but more tariffs and higher bills for the American consumer.
The trade deficit that has defined the American relationship with China for the last decade is not closing anytime soon. While the optics of high-level diplomacy change every few months the underlying mechanics of global trade remain stubborn. U.S. President Donald Trump and Chinese President Xi Jinping are set to meet this week for their second in-person summit of the year. The narrative leading up to the gathering focuses heavily on artificial intelligence and the geopolitical chessboard but the business community is looking for something far less dramatic. They are hoping for a simple extension of the trade truce reached last fall. However the data suggests that tariffs have done little to dent America's appetite for Chinese goods despite the political theater. The fundamental leverage of export pricing and supply chain dominance has not shifted in the slightest.
To understand why the United States remains dependent on Chinese manufacturing we must look at the sheer volume of the flow. Asia still accounts for more than 60% of U.S. imports. This figure remained unchanged even after the so-called Liberation Day tariff events according to Jens Eskelund president of the European Chamber of Commerce in China. Eskelund noted a fascinating logistical reality where between half and three-quarters of container traffic from China to Southeast Asia subsequently heads on to other destinations. This transit hub strategy has accelerated the pace at which the world relies on China-made goods. Eskelund previously expected China to account for 40% of global container exports in the year 2030. That specific financial milestone was actually reached this summer. The global container logistics network has been fundamentally reshaped by these shipping patterns creating a structural lock-in that is difficult to break.
The timeline of this economic shift is critical for investors and policymakers. Jens Eskelund suggested that the China shock only really started in 2022. He argued that everything was distorted by the pandemic. He observed that China was first in the pandemic and first out of the pandemic. This temporal advantage allowed China to allow its exchange rate to rise and export prices to rise. The logic here is simple. When demand is high and supply is constrained relative to the global market price increases naturally occur. China was the only game in town for a significant portion of that period. This allowed the country to weather the inevitable downturn in its domestic economy. The Chinese real estate market began its downturn in 2022 dragging down domestic demand. In response Chinese companies ramped up global expansion and exports to maintain GDP growth. There is a direct and perfect correlation between the drop in export prices and the acceleration in export volume terms according to Eskelund. When domestic consumption cooled the engine of export volume simply revved up to compensate.
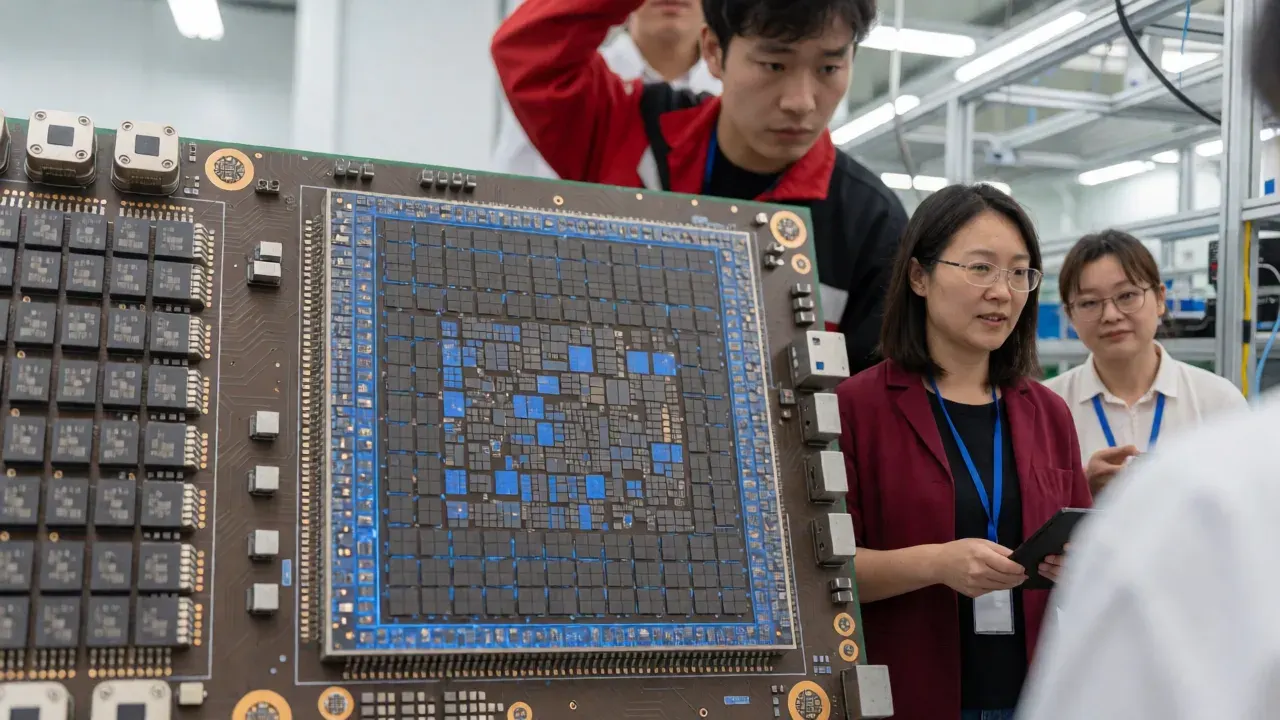
Technology represents the most volatile and rapidly evolving sector of this dynamic. U.S. tech companies have aggressively built out data centers to power artificial intelligence initiatives. This surge in capital expenditure has supported demand for specific categories of Chinese goods. However the outlook for high-tech exports is showing signs of fragility. Think tank CF40 estimated that for the first time this year AI-related exports fell significantly in August from a year ago. The semiconductor sector is acting as a leading indicator for this weakness. Macquarie's chief China economist Larry Hu pointed out that the recent performance of the PHLX Semiconductor Index tends to be predictive of how China's high-tech exports will grow in the next six months. Hu stated that the index "does not bode well for China's export outlook over the next year." This disconnect between the massive build-out of AI infrastructure and the cooling of hardware exports paints a complicated picture for the future.
Domestic economic indicators paint a picture of a market under stress yet not in crisis. Within tech-related manufacturing specific data points reveal a bifurcated economy. Industrial robot output rose by 34.6% year-on-year in August. This suggests a heavy investment in automation even as consumer demand softens. Conversely smartphone output fell by 22.3%. This divergence highlights the shift in consumer priorities away from hardware towards services or perhaps simply toward a slowdown in global consumerism. Goldman Sachs' chief China economist Hui Shan noted that because there are always high-flying subsectors for the government to point to policymakers do not appear to feel much urgency to introduce additional easing measures. The government can point to the robots or the AI chips as the engine of growth. However the human cost of this policy is visible in the housing market. House prices have already seen a 30% decline over a six-year timeline. This decline is typical of historical large-scale property downturns in other parts of the world. Hui Shan added that weak labor markets and still-falling rents are likely to prolong the downturn in many parts of China.
The financial health of the industrial base is also deteriorating. The number of loss-making companies is also on the rise. In 2025 these companies accounted for 24% of industrial firms in China. This percentage indicates a profitability squeeze that affects the entire supply chain. The economic slowdown has only pushed companies in China to compete even more fiercely with each other and their foreign rivals. The American Chamber of Commerce in Shanghai released survey data this month revealing a stark shift in perception. Three-quarters of members responding to the survey saw Chinese rivals as more advanced. The perceived gap in product quality narrowed by 6 percentage points from last year. This is a significant psychological shift for a market that once feared Chinese manufacturing out of necessity. For the first time since 2022 domestic competition has surpassed geopolitical tensions as the top challenge for members of the chamber. This suggests that the primary friction is now economic efficiency rather than political containment.
This internal pressure is spilling over internationally as the rest of the world recalibrates its trade strategies. European Union officials are starting to follow the U.S. in scrutiny of China-origin exports. EU Trade Commissioner Maroš Šefčovič urged "tangible results" from China on trade by October and is expected to travel to Beijing next month. The European Union has the largest trade deficit with China of any economy pointed out Jens Eskelund. The competition is no longer just about cheaper goods. Chinese companies have also come to dominate global supply chains for critical minerals. This vertical integration supports Beijing's self-sufficiency goals. The strategic calculus has changed from seeking reciprocity to managing asymmetry. "There is no sense in which China's strategy seems to be at all dependent on actions that the rest of the world might take" said Chad Bown senior fellow at the U.S.-based Peterson Institute for International Economics. He described it as "this strategy of a one-way dependence of the rest of the world on China that it's going to weaponize." The coming meeting between Trump and Xi will therefore be less about solving trade imbalances and more about managing a new reality of structural dominance.
First reported by CNBC: Finance.
More in Business
- IMF Chief Warns of Economic Divergence and Debt Risks Amid Artificial Intelligence Boom
Kristalina Georgieva suggests that while AI could significantly boost global growth, it simultaneously threatens to widen inequality and exacerbate inflationary pressures and public debt burdens.
- California Limits Utility Profits and Expands Home Energy Role
Gov. Gavin Newsom signed laws capping utility returns on lower-risk projects and accelerating virtual power plant development.
- Lyft to Pay $272.5 Million in Record California Wage-Theft Settlement
Largest such settlement in state history resolves claims that Lyft misclassified drivers as independent contractors from 2016 to 2020, denying them core wage protections.